Under-an-hour casino withdrawals in Australia
 Available in AU
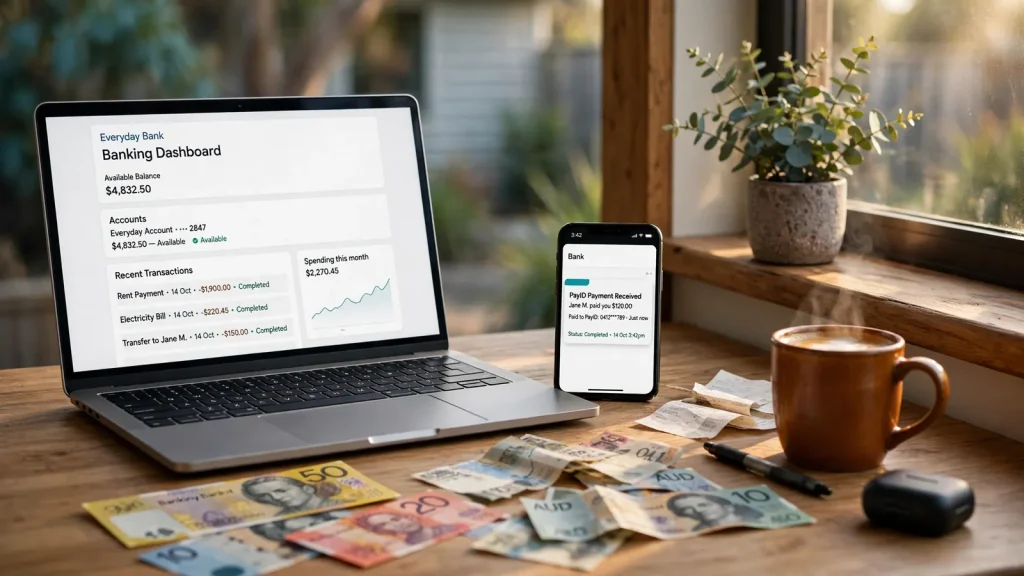
PayID can move a released payment promptly, but the casino’s review and decision to release it are separate steps.
Table of Contents
PayID Payouts: Instant After Approval, Not Before
The word “instant” can describe a narrow part of a withdrawal, not the whole journey from pressing a button to seeing money in a bank account. PayID is built for fast transfers between bank accounts. That does not mean a casino has approved a request, completed its checks or instructed a payment at the moment the request is made. The distinction is the hinge on which every under-an-hour claim turns.
PayID is Australia’s bank-to-bank payment system, operating through the New Payments Platform (NPP). Transfers use the Osko network, which supports real-time processing. Once a payment has been released into that network, the infrastructure can move it promptly. The casino’s decision to release it is a separate event, controlled by the operator’s own process.
That separation is easy to lose in a headline. A withdrawal can be described as instant because the transfer itself moves quickly, while the request waits in a queue before it is approved. The clock may therefore contain two very different stretches: an operator-controlled interval, during which a request is reviewed, and a payment interval, during which released funds travel through the banking system. Only the second is inherently associated with PayID’s real-time design.
Withdrawal times can depend on the payment method, so check the stated payout details before choosing a casino. This list highlights the information available for Australian players looking for withdrawals in under an hour.
1. Rollero Casino
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.)
Rollero Casino is listed with a Curacao Gaming Control Board licence, held by Hollycorn N.V.
2. WinSpirit Casino
License: Curacao eGaming OGL/2024/923/0383 (Antillephone N.V.) · Min. deposit: A$30
WinSpirit Casino is listed with a Curacao eGaming licence held by Antillephone N.V. Its minimum deposit is A$30.
3. Playfina Casino
License: Curacao eGaming (Hollycorn N.V., since 2017) · Min. deposit: A$20-30 (depends on the offer)
Playfina Casino is listed with a Curacao eGaming licence held by Hollycorn N.V., which has operated it since 2017. The minimum deposit is A$20–30, depending on the offer.
4. Thor Casino
License: Curacao – Antillephone N.V. (Versus Odds B.V.) · Min. deposit: EUR 20
Thor Casino is listed with a Curacao licence associated with Antillephone N.V. and Versus Odds B.V. Its minimum deposit is EUR 20.
5. LevelUp Casino
License: Curacao eGaming OGL/2023/174/0082 (Dama N.V.) · Min. deposit: A$15
LevelUp Casino is listed with a Curacao eGaming licence held by Dama N.V. The minimum deposit is A$15.
6. Bizzo Casino
License: Curacao Gaming Control Board (TechSolutions Group N.V.)
Bizzo Casino is listed with a Curacao Gaming Control Board licence held by TechSolutions Group N.V.
7. Lucky Dreams
License: Curacao · Min. deposit: A$20 (POLi)
Lucky Dreams is listed with a Curacao licence and a minimum deposit of A$20 via POLi.
8. SpinsUp
License: Curacao Gaming Control Board OGL/2023/174/0082 (Dama N.V.)
SpinsUp is listed with a Curacao Gaming Control Board licence held by Dama N.V.
9. Ricky Casino
Payout speed: crypto under 1 hour, PayID 1-3 business days · Min. deposit: A$20 (A$30 to qualify for the bonus)
Ricky Casino lists crypto payouts in under an hour, while PayID withdrawals take 1–3 business days. The minimum deposit is A$20, or A$30 to qualify for the bonus.
10. House of Pokies
License: international iGaming licence – jurisdiction not named in the source · Payout speed: PayID 1-24 hours · Min. deposit: A$30 (PayID from A$10)
House of Pokies lists PayID withdrawals in 1–24 hours. Its minimum deposit is A$30, with PayID deposits available from A$10; the jurisdiction of its international iGaming licence is not named.
A report on PayID withdrawals by filmink.com.au likewise describes them as almost immediate in contrast with bank transfers that can take several working days. That comparison concerns the movement of money after release; it does not establish that every request is approved at once. The distinction is not a technical footnote. It is the difference between the advertised speed of a payment rail and the time a customer actually waits.
What the clock measures
A withdrawal request begins inside an operator’s systems. It may be received, placed in a pending state, checked, approved and then sent for payment. The bank-to-bank transfer network cannot speed up stages that happen before the operator releases funds. A real-time rail is not a real-time review department.
This matters particularly when the phrase “under an hour” is treated as a single promise. A stated time might refer to a typical transfer after approval, a measured interval from request to receipt, or a selected set of transactions in which no extra checks were needed. Those are not interchangeable measurements. Without knowing where the clock starts and stops, a speed figure describes less than it seems to.
The most defensible reading of “instant withdrawal” is therefore limited: instant refers to the payment phase after operator approval, not a guarantee that the entire process from request to receipt will be completed immediately. Casino terms should make that boundary clear. If a request is still being reviewed, the payment phase has not begun, however quickly the network could handle the eventual transfer.
The division also explains why two customers using the same payment method may experience different waits. PayID describes the route funds take once sent. It does not tell whether the operator has completed its internal review, whether the request is eligible for automatic approval or whether the receiving account details match the account on the customer profile. The rail can be consistent while the release decision is not.
There is a small but important change of agency in the wording. “PayID is instant” sounds as though the method controls the entire transaction. In practice, the operator controls when it sends the payment; the payment system controls what happens once the transfer enters its network. The first party can pause. The second is designed to move funds in real time. Blending those actions into one promise makes the slower part disappear from view.
What reported speeds can—and cannot—show
A specialist review of Australian PayID casinos reported that the options it assessed processed withdrawals in under five minutes, while standard bank transfers were described as taking one to three business days. Another specialist review gave an average range of 30–90 seconds for the PayID options it considered. These figures are reports about particular assessments, not a standing service standard for every operator or every withdrawal.
Fastpay Casino
Reported average withdrawal time of 47 seconds.
PlayAmo
Reported average withdrawal time of 68 seconds.
National Casino
Reported average withdrawal time of 3.2 minutes, attributed to security checks on first withdrawals.
A separate specialist review recorded averages of 47 seconds for Fastpay Casino and 68 seconds for PlayAmo, while its figure for National Casino was 3.2 minutes. The review attributed the longer result at National Casino to security checks on first withdrawals. These are attributed observations, not a guarantee that the named services will reproduce those times for another person, on another day, or under different account conditions. Nor do those reported results establish that those services are lawful for people in Australia.
That final point is not incidental. Under Australia’s Interactive Gambling Act 2001, operators may not provide real-money online casino games to people physically in the country. The prohibition covers casino-style services such as slots, poker, blackjack and roulette. Real-money online casinos are not a lawful Australian service category, and access to offshore services is actively blocked and enforced. A report about an asserted payout speed should not be mistaken for an invitation or an assurance of availability.
The figures still illustrate the gap between a payment rail’s capability and a platform’s handling of a transaction. A reported transfer measured in seconds may reflect a request that had already cleared review. A longer average may include security checks, or may be calculated from a different sample. The number alone cannot reveal how many requests were delayed, what counted as the start of the measurement, or how much time elapsed before approval.
One specialist review also reported that some sites advertising “instant” withdrawals took as long as 24 hours because of internal review processes. Again, the finding is specific to that review, not a universal description of the market. Its useful lesson is more modest: a label attached to the payment method can coexist with a substantial wait before payment is sent.
Fast Withdrawal Casinos in Australia: Payment Routes
A reported average is not a promise to each customer. It condenses a set of observations into a single figure, leaving out the shape of the individual experience. A quick transaction may be memorable and easy to advertise; a pending request is less photogenic. The number is useful only when its scope is understood: which stage was timed, which transactions were included and whether the reported result belongs to an independent review or to an operator’s own description.
That is why a claim of payment in seconds should not be silently translated into “cash in the account in seconds.” The first statement may concern a completed transfer; the second includes all the decisions and checks that precede it. A time estimate that does not distinguish these stages risks being technically true and practically misleading at the same time.
The approval gate
Operator review is not an accidental interruption to PayID. It is a separate part of handling a withdrawal request. A specialist review identified first-time identity verification, larger requests and bank processing windows among possible sources of delay. In its account, requests exceeding $2,000 were one point at which delays could arise. That is a reported observation, not a universal threshold or a rule shared by every service.
A different specialist review reported automatic approval for withdrawals below $5,000 AUD at top-tier Australian PayID casinos. That too is a specific claim attributed to a review, not a general property of PayID. Automatic approval, where an operator offers it, means the operator has arranged for some requests to pass through without the same manual step. It does not make every request eligible, abolish identity checks or turn the payment network into the party authorising the withdrawal.
Reported automatic approval thresholds vary by operator, with some reviews citing limits of $2,000 and others mentioning under $5,000 AUD at top-tier services.
The contrast between the reported $2,000 delay point and the reported under-$5,000 auto-approval policy is a reminder not to treat figures from separate reviews as parts of one universal schedule. They describe different assessments and possibly different operators, criteria or transactions. One cannot be used to infer that a request of a particular size will be delayed or approved elsewhere. The relevant terms and actual process belong to the service handling the request.
A review can also be triggered by facts that have little to do with the payment rail. If account details do not line up, an operator may need to examine the transaction before release. A first withdrawal can involve checks that do not recur in the same way on later requests. A mismatch or incomplete account record may turn a request that would otherwise pass through a routine process into one that needs attention. These are questions of account handling and operator procedure, not failures of the NPP or Osko.
The identity of the payment route should not be mistaken for identity verification. PayID can identify a recipient through a bank-linked identifier, but that does not itself establish that the person making a withdrawal has completed the operator’s required checks. A payment address is not a substitute for a verified account. The bank network’s ability to route funds says nothing about whether the operator has authorised the release.
The phrase “automatic approval” can also give a false impression of finality. It describes an approval step, not an unconditional right to receive funds or a promise that no review will ever occur. A request can fall outside the operator’s stated conditions or raise a question that requires manual attention. Even an automated process remains bounded by the rules and information on which it operates.
For the same reason, the fastest reported examples should be read with restraint. A specialist review’s seconds-long results may demonstrate that a short end-to-end interval is possible in the circumstances it measured. They do not show that every request is handled that way, that an account will qualify for the same path, or that the service is legally available to Australian residents. Speed data is a description of observed handling, not a guarantee.
Where an “instant” claim can stall
The most common conceptual mistake is to imagine one continuous action: request, approval, transfer, receipt. The real process has a handover. Until approval, the operator still holds the decision. After release, the payment system can carry out the transfer. A delay before that handover cannot fairly be attributed to PayID’s network, even if the overall experience is marketed under PayID’s name.
Internal review is one possible pause. A specialist review reported cases in which an advertised instant withdrawal took up to 24 hours because of such checks. That does not mean every review lasts that long; it means the claim “instant” did not describe the entire interval in those reported cases. In a transaction with no review delay, the same payment route may appear dramatically faster. The label remains the same while the underlying sequence differs.
Do
- Distinguish between payment rail speed and operator approval time
- Account for security checks on first-time withdrawals
Don’t
- Assume “instant” covers the entire process from request to receipt
- Treat reported average speeds as a universal guarantee
Identity checks can be another dividing line. The specialist review that discussed the 47-second and 68-second averages reported a longer 3.2-minute average for National Casino and linked it to first-withdrawal security checks. The comparison makes the point without making the figures universal: a security step can add time even when the eventual payment method is designed for real-time movement. The review’s explanation also shows why a first transaction may not be a useful forecast for every later one.
Amounts can matter under particular operator policies. The specialist review that listed common delays included withdrawals above $2,000, while another review described automatic approval below $5,000 AUD at top-tier services. These reported figures should not be fused into a single rule. They do not establish that every request above one threshold is held, or that every request below another is automatically cleared. They show that eligibility and review can be tied to an operator’s own limits and controls.
Bank processing windows may also affect the observed wait, according to the specialist review that discussed common delays. PayID’s underlying design is for real-time movement, but an operator’s handling, a receiving bank’s processes or the moment a transfer is initiated can influence what a person experiences. The word “real-time” describes the payment infrastructure; it does not promise that every institution’s surrounding process will be invisible.
Even the status displayed on a withdrawal page can obscure the handover. “Pending” might mean the request has not yet been examined, or that a review is under way. “Approved” may indicate the operator has authorised it but not yet sent the funds. “Processed” could refer to a payment instruction rather than confirmation that the receiving account has credited it. The exact labels depend on the service, so a status word on its own is not a reliable stopwatch.
This is why advertised speed needs a defined starting point. If a claim begins when a payment is released, it says little about the time spent in the queue beforehand. If it begins when a withdrawal is submitted, it is an end-to-end claim and should include the operator’s review stage. A clear statement separates those two measurements rather than borrowing the speed of the payment rail to describe the whole experience.
The word “instant” can therefore be accurate in one narrow sense and inadequate in another. A transfer may move almost at once after approval, while a request remains unapproved for longer. The word has not changed; its subject has. In financial language, that is a small omission with large consequences.
A payment rail, not a release decision
PayID is useful to understand as infrastructure rather than as a promise made by a casino. It links a bank-to-bank transfer to an identifier and operates through the NPP, with Osko handling real-time processing. In that sense, it offers a route capable of moving funds quickly once the sender has initiated the payment. It does not set an operator’s review timetable or determine whether a withdrawal is cleared.
Legal Prohibition
Under Australia’s Interactive Gambling Act 2001, providing real-money online casino games to people physically in the country is prohibited.
This is also why comparisons with standard bank transfers need careful wording. Specialist reviews have contrasted reported PayID processing in under five minutes with bank transfers taking one to three business days, and filmink.com.au has described PayID payments as almost immediate beside bank transfers that may take several working days. Those comparisons can describe the speed of the payment phase. They do not establish that a withdrawal request through PayID will be approved more quickly than every request sent by another method.
Payment speed is only one part of a withdrawal experience. A fast transfer after release cannot recover time spent waiting for the operator to act. Conversely, a review that clears quickly makes the payment rail’s speed more visible. The route and the release process interact, but they are not the same mechanism.
It is tempting to regard this distinction as technical housekeeping. It is more than that. A payment method is a piece of public financial infrastructure; a withdrawal policy is a private operator’s decision. When the latter borrows the former’s reputation for speed, the customer can be left with an appealing promise whose boundary was never stated. The fast system is real. So is the queue.
The Australian legal setting makes neutral description especially important. Real-money online casino games, including poker, slots and table games, are prohibited when offered to people physically in Australia, and offshore services are actively blocked and enforced. Nothing about the availability of PayID as a general bank payment system changes that rule. Nor does a reported payout time establish that a particular real-money service may lawfully offer casino play in Australia.
Online Pokies Instant Withdrawals in Australia
The result is a narrower, more accurate meaning for the headline word. PayID can support rapid movement after the operator releases a payment; it cannot make the operator release it immediately. Reports of seconds-long transfers and reviews describing waits for internal checks can both be true, because they measure different parts of the same chain. The approval gate comes first. The network comes after.
Instant after approval. Not before.
Real-Money Withdrawals Depend on the Payment Route
A payment method can describe how funds travel, but it does not establish whether a real-money casino service may lawfully be provided in Australia. The Interactive Gambling Act 2001 prohibits operators from providing online casino games, including slots, poker and table games, to people physically in the country. The payment routes discussed here appear in descriptions of offshore services; their availability does not change that legal position.
The route matters because a withdrawal has more than one stage. An operator must first release the funds; only then does the payment network or provider carry them onward. A fast transfer mechanism cannot make an operator’s processing instant. Nor does a payment option shown for deposits necessarily work in reverse for withdrawals.
E-wallets
PayPal and Skrill are among the e-wallets named in specialist descriptions of payment options for Australian players. An e-wallet can sit between a casino account and a bank account, so its withdrawal timing is distinct from the time taken for the operator to approve a request.
One specialist review describes e-wallet transactions as completing within hours rather than days. Another general timing account puts e-wallet withdrawals within 24 hours. These are reported timeframes, not a guarantee for a particular transaction: approval and the provider’s own handling remain separate steps. The convenience of a digital wallet does not erase the queue before funds are sent.
E-wallet withdrawal timeframes
Specialist reviews report that e-wallet transactions may complete within hours or within a 24-hour window, though these remain separate from the operator’s approval process.
Bank transfers and cards
Bank transfers are another route identified in descriptions of available payment methods. They are less suited to an expectation of immediate receipt: one specialist review says a traditional transfer can take as long as five business days. A separate timing account describes bank transfers as potentially taking several days. The exact timing can depend on the operator’s release and the banks involved.
Credit and debit cards also appear in general descriptions of payment options, but the Australian legal context is decisive: credit card payments must not be accepted for online gambling services. A mention of cards in a payment-method list should not be read as permission to use credit cards for prohibited casino gambling. Card transactions may also take several days, according to the general timing account; a card route is not synonymous with an instant payout.
A prepaid voucher has a different limitation. A specialist review describes vouchers such as Neosurf as generally serving deposits rather than withdrawals. That distinction matters: money can enter an account through one instrument while winnings, where a service offers them, have to leave through another route.
Instant banking and cryptocurrency
Some specialist descriptions say that certain services offer instant banking through providers such as POLi. “Instant” in this setting characterises the banking connection, not every step from a withdrawal request to money reaching an account. It says nothing by itself about how long an operator takes to approve or release funds.
Cryptocurrency is also listed by some descriptions of casino payment options. A specialist review characterises crypto transactions as potentially near-instant, but that refers to the transfer mechanism, not an assured end-to-end withdrawal time. The operator’s processing and the receiving wallet or exchange still form part of the journey.
These routes are not interchangeable. E-wallets have their own provider stage; bank transfers rely on banking processes; card payments are subject to both card handling and the legal restriction on credit-card gambling payments; vouchers may not support cashouts; and crypto has its own transfer path. The label attached to a payment method is only one part of the timing.
The measure that matters
Timing claims can blur together three different events: a withdrawal request, the operator’s release of funds, and the arrival of money through the chosen route. A method may move funds quickly after release while the full process takes longer. Conversely, a service described as instant banking does not establish that a withdrawal request will be approved immediately.
That distinction is particularly important in Australia, where the underlying provision of real-money online casino games to people in the country is prohibited. Payment options described by offshore services do not make those services lawful or imply that they are available for residents to use. Speed is a property of a transfer stage, not a verdict on the service behind it.
Withdrawal Timing
- Payment route speed refers to the transfer phase after operator approval
- E-wallets and crypto can be faster than traditional bank transfers
- Operator reviews and legal restrictions are independent of the payment method’s technical speed
What to Check Behind an Under-an-Hour Payout Claim
An “under an hour” promise can describe only part of a withdrawal. The clock might start after an operator approves a request, not when the request is submitted; it might stop when funds leave the operator, rather than when they appear in a bank account. Those are different milestones, even when a headline compresses them into one confident phrase.
That distinction matters especially for PayID. Its infrastructure supports transfers between bank accounts in real time, but that does not make an operator’s decision-making real time. A claim about the payment route cannot, on its own, establish how long a request will wait for review or whether a particular transaction will be released promptly. “Instant” needs a defined starting point.
There is another boundary around the claim: real-money online casino games are prohibited services for customers physically in Australia under the Interactive Gambling Act 2001. A payout advertisement does not alter that legal position. Nor does a fast transfer turn an offshore casino into a service lawfully offered to Australian residents. The distinction is not a technicality; it is the part of the arrangement that a payment-speed headline tends to leave outside the frame.
Read the clock, not just the headline
A useful speed statement identifies which stage it measures. Does the stated time refer to the operator approving the withdrawal, sending the payment, or the money becoming available in the receiving account? If those stages are bundled together, the claim is difficult to assess. The time spent in an internal queue may be quite separate from the time taken by a payment network.
Same-Day Casino Payouts in Australia: The Process
A specialist review has reported that some sites advertising instant withdrawals took as long as a day because of internal checks. That account is not a universal timetable, but it illustrates why the word “instant” should not be read as a promise covering the entire journey. A payment method can move funds quickly after release; it cannot decide when a business releases them.
It also helps to distinguish a stated processing target from a guarantee. A policy may describe an intended time while reserving room for review, technical interruption or other exceptions. The terms should say what happens when the stated window is missed and whether the operator’s time estimate begins at submission or approval. Vague wording makes a short headline easy to print and hard to verify.
Check both kinds of limit
The amount requested can affect whether a speed claim applies. Casino policy may set a minimum or maximum for a single withdrawal, and those terms can make a headline’s apparent promise narrower than it first appears. A specialist review has noted that reputable PayID operators publish minimum and maximum withdrawal limits clearly; the practical test is whether those limits are easy to find and whether they are attached to the advertised timing.
A per-transaction maximum is not necessarily the whole picture. A separate weekly or monthly cashout ceiling may restrict how much can leave an account over a longer period. A request can therefore fit within the single-payment limit while still being affected by a broader cap. If a large balance must be divided into instalments under an operator’s policy, the first transfer’s speed says little about how quickly the full balance will be received.
Verify Payout Terms
- Check the minimum and maximum limit for a single withdrawal
- Identify any weekly or monthly cashout ceilings
- Confirm if the stated timing applies to each instalment or the total balance
- Check for any fees associated with the chosen payment method
Limits should be read together, not treated as interchangeable figures. Look for the minimum, the maximum for one request, and any period-based ceiling, then check whether the stated time applies to each instalment or to the payout as a whole. A clear policy makes these distinctions visible. A headline does not.
Look for fees beside the timing
A quick transfer is not necessarily a cost-free one. A report published by filmink.com.au notes that a fee may apply when funds are withdrawn through PayID. That is a possibility to check in the relevant terms, not a basis for assuming every operator charges one. The amount, who imposes it and when it is deducted should be stated plainly.
Fees can also change the meaning of the amount received. If a policy says a withdrawal is processed promptly but is unclear about deductions, speed alone gives an incomplete account of the transaction. The terms should explain whether any charge comes from the operator or another part of the payment process, and whether the amount displayed before confirmation is the amount expected to reach the account.
The same caution applies to language such as “free” or “no fee”: it should be clear which transaction the wording covers. A deposit offer, a transfer between accounts and a withdrawal are not necessarily governed by identical conditions. Specific wording is more useful than a general badge.
Treat a claim as a set of conditions
A credible payout statement is precise about the stage measured, the applicable withdrawal limits and any fees. It does not turn a fast payment network into a guarantee that an entire request will be completed inside the same short window. The details belong in the terms and conditions, not only in promotional copy.
Speed is one part of a transaction. Limits and charges are another; legal status is separate again. For Australian residents, that last distinction is decisive: the Interactive Gambling Act prohibits online casino-style services being provided to people in Australia. A claim about a rapid payout should not be mistaken for permission, protection or a lawful local offer.
When a Casino Can Release Real-Money Winnings
In Australia, the conditions attached to a withdrawal sit within a larger legal fact: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games to people physically in the country. Offshore services may still appear online, but their presence does not make them lawful offerings in Australia. The practical details below describe the kinds of account checks such services may impose; they are not an endorsement or an invitation to use them.
A withdrawal request is not simply an instruction to send money. Before funds can be released, an operator may need to establish who owns the account, whether the payment details match, and whether any bonus conditions remain outstanding. These checks concern the operator’s records as much as the payment itself. A fast transfer system cannot resolve a mismatch in those records.
Withdrawal Process
Identity Verification
The operator performs KYC checks to verify the account holder’s identity.
Detail Matching
The operator ensures the PayID details match the deposit record and casino profile.
Condition Review
The operator checks if all wagering requirements for bonus funds have been met.
Fund Release
Once approved, the operator releases the funds into the payment network for transfer.
Identity checks before payment
Identity verification, commonly called KYC, is a basic condition of withdrawal processing. A casino must verify a player’s identity before processing a withdrawal. The first request may therefore prompt a request for documents or other confirmation, even if deposits and gameplay have already taken place. A specialist review reports that first withdrawals often trigger such checks; this is a reported pattern, not a guarantee about what any particular service will request.
Completing verification early can significantly reduce friction on later withdrawals. The reason is practical: a pending identity check can hold up approval before the payment method is involved at all. Once a request reaches that stage, the speed of the transfer network is beside the point. The money has not yet been released.
The details provided for verification should be consistent with the account and payment profile. Differences in names or account ownership can lead to further scrutiny, because the operator must determine whether the withdrawal is going to the person entitled to receive it. A request for additional information does not, by itself, establish that a payment has been refused; it means the operator has not finished its checks.
PayID details and linked accounts
Payment details are another part of the identity trail. Operators generally require funds to be returned to the method used for the deposit where that is possible. For PayID, the details used for a withdrawal should match those used for deposits, and the destination account must be linked to the casino profile. Using different PayID details can trigger a security review rather than a quicker route to payment.
That restriction reflects a wider financial concern: funds should travel back to an account the operator can associate with the verified customer. A PayID identifier is not a substitute for matching ownership. If the identifier, account profile and verified identity do not align, an operator may need to pause the request and investigate.
Quick Casino Withdrawals in Australia: How They Work
PayID operates through Australia’s New Payments Platform, which enables real-time transfers between bank accounts. That describes the payment infrastructure, not the operator’s approval process. An account can be capable of receiving a rapid transfer while a withdrawal remains held for identity or account checks. “Instant” is not a magic word that cancels paperwork.
Bonus conditions and withdrawable funds
Bonus funds can add another condition. Wagering requirements may apply to the bonus alone or to the combined deposit and bonus, depending on the terms attached to the offer. A specialist review describes bonus-only wagering as preferable because it places the requirement on the bonus funds rather than the player’s deposit as well. The terms determine which balance is affected and what must be completed before funds become withdrawable.
A balance displayed on screen is not necessarily a balance available for withdrawal. If a wagering condition remains unmet, a request may be rejected, delayed or limited under the offer’s rules. The distinction matters: identity checks establish who is making the request; bonus terms establish whether the requested funds have cleared the conditions attached to them. Neither is a payment-speed issue.
The terms should make clear what applies to bonus funds and whether the deposit is included in the wagering calculation. If that wording is unclear, the amount shown as a balance cannot settle the question. Account conditions govern release.
Why a first request can take longer
The first withdrawal brings these strands together. Identity verification may still be pending; the PayID details may not match the deposit record; or bonus requirements may not be complete. Each can prevent an operator from approving a request, even when the payment route itself supports near-instant transfers. Later withdrawals may proceed with less friction if verification is already complete and the account and payment details remain consistent.
For Australian residents, there is also a boundary that payment mechanics cannot erase: real-money online casino games are prohibited services when provided to people in Australia. The absence of player liability is not the same as a lawful local casino market. A withdrawal promise on an offshore service does not alter that distinction.
What are easy withdrawal casinos?
They are services that process cash-outs quickly, often using PayID for near-real-time transfers after approval. However, real-money online casinos are not a lawful service category for people in Australia.
How do you choose the best easy withdrawal casino site?
Check the published withdrawal limits and fees, whether withdrawals can be auto-approved, and what identity checks are required. Fast payment methods cannot eliminate operator review, and real-money online casinos are not lawful for people in Australia.
How fast are withdrawals?
PayID transfers can arrive in real time once the operator releases them; reported averages for some options were 30–90 seconds. Approval and checks can add time, with some advertised instant withdrawals taking up to 24 hours; bank transfers can take up to five business days.
What payment methods are available?
Options listed include credit and debit cards, PayPal and Skrill, bank transfers, and, at some casinos, cryptocurrency. PayID and POLi are also mentioned for instant banking, while prepaid vouchers such as Neosurf are generally for deposits rather than withdrawals.
Payments
Anonymous Crypto Casinos in Australia: Fees and Access
Bitcoin and other crypto options bring payment, privacy and access trade-offs for Australian casino users....
Aristocrat Online Pokies in Australia: What’s Verifiable
Brand names and casino listings alone do not establish a game's origin, online availability, or...
Aussie Crypto Casinos: Payments, Risks and Rules
A practical look at payment choices, operator boundaries, promotional terms and the limits of claims...
New Australian Online Pokies: Legal and Payment Checks
A practical look at legal limits, verification, bonus conditions and payment issues surrounding offshore real-money...
Online Casino Payment Methods for Australian Players
Payment options differ in how deposits are accepted, withdrawals are handled and funds move between...
Online pokies in Australia: what “best-paying” means
A practical guide to interpreting payout claims, distinguishing free play from real-money play, and understanding...
Bitcoin Pokies in Australia: Payments and Risks
Bitcoin is a payment method, not a feature that defines a game's software or outcome;...
Casino Sites That Accept Amex in Australia
Amex availability can depend on the casino, payment provider, card issuer and transaction, while withdrawals...
Casino sites that accept BPAY in Australia: what’s known
Australian payment language does not establish that a casino is locally authorised or that BPAY...
Australian casino sites that accept credit cards
Card acceptance can enable a deposit, but it does not establish that an offshore casino...
Casino Sites That Accept EcoPayz in Australia: Key Checks
EcoPayz availability, cashier terms and withdrawal timing do not establish that an offshore casino may...
Casino Sites That Accept Osko in Australia: Evidence
The article distinguishes Australian casino terminology from payment evidence, including why a search phrase alone...
Paysafecard at Australian casino sites: what is verified
Mentions of Australian pokies, local payment preferences and cashier options do not by themselves establish...
Skrill for Australian Casino Sites: What Can Be Verified
Skrill acceptance is specific to an operator and transaction, while Australian rules place responsibility for...
Trustly casino sites in Australia: checking claims
Everyday payment habits and a Trustly label do not, on their own, confirm that a...
No-Verification Casino Withdrawals in Australia
Registration claims do not settle cashout rules: identity checks, payment processing and bonus conditions can...
Casinos That Accept Apple Pay in Australia
Australian contactless habits do not establish which online casinos accept Apple Pay or what their...
Casinos That Accept Bitcoin in Australia: Rules & Risks
Bitcoin can change how deposits and withdrawals work, but it does not make an offshore...
Casinos accepting Bitcoin Cash in Australia: a guide
BCH is a payment method, not a legal exemption; offshore access, game availability and withdrawal...
CashtoCode Casinos in Australia: What Can Be Verified
The Interactive Gambling Act 2001 bars operators from offering online casino games to people in...
Casinos That Accept Ethereum in Australia: What’s Verifiable
Ethereum may offer fast, low-fee transfers in general, but that does not confirm availability or...
Casinos That Accept Google Pay in Australia
Familiarity with mobile wallets does not prove an online casino accepts Google Pay or supports...
Casinos That Accept Litecoin in Australia: Legal Limits
The law, payment claims and account checks are considered separately, since accepting Litecoin does not...
Casinos That Accept Mastercard in Australia
Everyday card use in Australia does not establish which online casinos accept Mastercard or whether...
Casinos That Accept MiFinity in Australia: What to Know
Payment acceptance cannot establish whether an offshore casino may legally offer real-money games to people...
Casinos That Accept Neosurf in Australia: What to Check
A search result or casino label alone cannot establish Neosurf availability, permitted use, or withdrawal...
Casinos That Accept Neteller in Australia: What to Know
A careful look at how Neteller, pokies, Australian audiences, deposits, withdrawals and bonus claims are...
Casinos That Accept PayID in Australia: What to Check
The article examines the limits of evidence on PayID acceptance, deposits and withdrawals at casino...
Casinos That Accept PayPal in Australia: What to Know
PayPal availability, withdrawal options and a site's legal status are separate questions when assessing Australian-facing...
Casinos That Accept POLi in Australia: Legal Limits
Payment-menu claims do not establish legality, and the available evidence does not confirm whether casinos...
Casinos That Accept Tether USDT in Australia
The article distinguishes general crypto-payment claims from what is known about Tether, casino terms and...
Casinos That Accept Visa in Australia: What to Know
Visa's everyday use in Australia does not establish casino acceptance, withdrawal processing, or the legality...
Dragon Link Online Pokies in Australia: Bitcoin Context
A pokie describes a digital slot game, while Bitcoin describes a payment method; the name...
Easy Withdrawal Casinos in Australia: How Payouts Work
Withdrawal speed depends on operator approval as well as the payment method, and Australian law...
Fast Withdrawal Casinos in Australia: Payment Routes
Withdrawal timing depends on casino processing as well as the payment network, while limits, fees...
Instant Bank Transfer Casinos in Australia
Bank transfer options can differ in how they fund an account, handle withdrawals and fit...
Real-Money PayID Withdrawals in Australia: How Fast?
PayID can move bank-to-bank payments in real time, but the operator must release a withdrawal...
Instant PayID Withdrawals in Australia: How They Work
PayID can move released funds in real time, but casino reviews, first withdrawals and wagering...
PayID Pokies in Australia: Payments and Legal Context
The guide distinguishes payment mechanics from legality and explains deposits, withdrawals, limits and bonus conditions...
No-KYC Casinos in Australia: Checks and Payouts
The label may describe signup, but it does not rule out identity checks when a...
Online Pokies Instant Withdrawals in Australia
A withdrawal depends on operator checks and release as well as the speed of the...
Online Pokies PayID in Australia: How Payments Work
PayID is an identifier used through the New Payments Platform, but acceptance alone does not...
Pay by Phone Casinos in Australia: PayID Explained
The guide distinguishes carrier-billed charges from bank payments and explains why payment approval, bonuses and...
Quick Casino Withdrawals in Australia: How They Work
Payment speed depends on the transfer method, casino terms, identity checks and whether a deposit...
Real Cash Online Pokies in Australia: Bitcoin Play
Bitcoin changes how deposits are made, but game credits, bonus terms and offshore protections determine...
Safe Online Pokies in Australia: What Safety Means
The guide separates account and payment safeguards from legal status, and explains Bitcoin transfers, offshore...
Same-Day Casino Payouts in Australia: The Process
A withdrawal moves through operator checks and payment rails, so “same day” may describe release...
Solana Casino Comparison for Australia
Follow the exchange-to-wallet path and assess legal uncertainty, bonus terms, token exposure and withdrawal conditions....